
Michael Horbal is the founder of RiskQuoter.com, an independent life insurance agency specializing in high-risk applicants. His goal is to help consumers find the best life insurance rates possible by matching them with the right insurer.
Finding life insurance after thyroid cancer can feel intimidating. Many people assume a cancer history means automatic denial…
But that’s not the case. In fact, thousands of thyroid cancer survivors secure affordable coverage every year.
In this guide, you’ll learn everything you need to know about getting life insurance after cancer — from eligibility to sample rates, underwriting questions, and the best companies to apply with.
1. Can You Get Life Insurance With Thyroid Cancer?
Yes, you can. Most thyroid cancer survivors are eligible for high-risk life insurance once their treatment is complete. Your eligibility depends on:
- Type of thyroid cancer (papillary, follicular, medullary, or anaplastic)
- Stage and size of the tumor
- Treatment received (surgery, radiation, radioactive iodine, etc.)
- Time since last treatment
- Recurrence history
Case study: A 45-year-old woman treated for papillary thyroid cancer with surgery in 2018 was approved for a 20-year $250,000 term policy at standard non-tobacco rates. Her remission period and clean follow-ups made approval possible.
Bottom Line: Papillary and follicular thyroid cancers are considered the lowest risk, with many survivors approved for standard or even preferred rates. Medullary and anaplastic thyroid cancers are higher risk, often requiring guaranteed issue life insurance.
2. How Different Types of Thyroid Cancer Affect Life Insurance
The type of thyroid cancer you were diagnosed with has a direct impact on your rates:
- Papillary thyroid cancer – Most common and least aggressive. Survivors often qualify for standard rates immediately after treatment and may be eligible for preferred rates in the future.
- Follicular thyroid cancer – Slightly more aggressive than papillary, but still favorable for underwriting if treated early.
- Medullary thyroid cancer – Less common and higher risk, especially if there’s a family history or genetic factors. Standard rates may be possible, but many cases are rated or postponed.
- Anaplastic thyroid cancer – Rare and very aggressive. Guaranteed issue life insurance is the only option.
Key insight: Insurers heavily weigh cancer type, stage, and remission length when deciding rate classes.
3. What Will Life Insurance Cost After Thyroid Cancer?
Premiums are higher than for people without a cancer history, but they can improve with time. The best rate you’ll ever get will be a “standard plus”, and possibly a “preferred” rate for stage 1 thyroid cancer.
Here are some common underwriting outcomes.
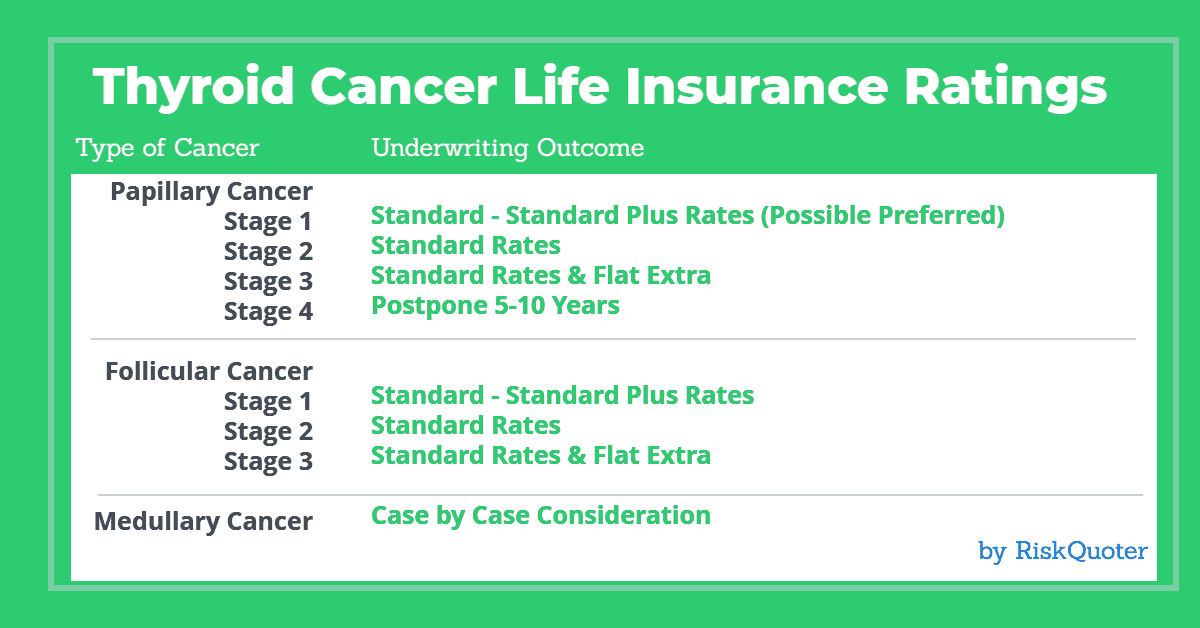
Tip: The underwriting rate class you qualify for tends to improve over time. It’s wise to shop the market each year for a better rate.
Underwriting terms you may encounter include table ratings and flat extras, which are expenses added to your policy price, depending on the specifics of your medical history.
4. Best Life Insurance Companies for Thyroid Cancer Survivors
Not all insurers underwrite cancer histories the same way. Some specialize in high-risk applicants, while others decline immediately.
Top carriers for thyroid cancer survivors include:
- Prudential – Strong with thyroid and other cancers, flexible underwriting.
- Mutual of Omaha – Competitive rates for standard-risk approvals.
- Lincoln Financial – Good for those past the 5-year remission mark.
- Pacific Life – Often favorable for younger survivors.
- Banner Life – Standard Plus rates are possible.
- Protective Life – Budget-friendly term coverage with conversion options.
Insider tip: As independent brokers, we work with dozens of carriers to shop your case, saving you the hassle of applying to multiple companies.
5. Underwriting Questions for Thyroid Cancer
We’ll ask you detailed medical questions to ensure that the quotes you receive are accurate.
- How old were you when you were diagnosed with thyroid cancer?
- What type of thyroid cancer was diagnosed?
- What stage and size was the tumor?
- What treatments did you undergo (surgery, radiation, radioactive iodine)?
- When did you start and end treatment?
- Have you had any recurrences or metastasis?
- What are your latest follow-up results?
- Are you currently taking any thyroid medications?
- Additional factors insurers consider:
Pro tip: The more details you provide upfront, the more accurate your quotes will be.
6. Policy Options Available to Thyroid Cancer Survivors
Depending on your health and time since completing treatment, you may qualify for:
- Term Life Insurance – Best for affordable coverage (10–40 years). Often available 3-12 months post-treatment.
- Guaranteed Universal Life Insurance – Guaranteed death benefits and premiums to age 120.
- Whole Life Insurance – Lifetime coverage with cash value. More expensive, but guaranteed.
- Guaranteed issue life insurance – No medical questions, available up to age 80. Last-resort option for those who have been recently treated or have a recurrence.
- Group life insurance – Employer-provided, usually easier to qualify for but limited in amount.
Key Insight: The policies and prices available will vary by company. We’ll show you all the options.
7. Tips for Applying With a Thyroid Cancer History
Tips to Improve Approval Odds:
- Shop around – One company’s decline may be another’s approval.
- Work with a specialist -We know thyroid cancer and which companies are best.
- Be honest – Full disclosure is essential. Medical records are checked.
- Time matters – Better rates become available as more time passes since treatment.
- Maintain/Improve health – Quit smoking, manage weight, blood pressure, etc.
Tip: The biggest mistake survivors make is applying to the wrong company.
8. FAQs About Thyroid Cancer and Life Insurance
Yes, you can often obtain life insurance within a few months of surgery.
Life insurance depends on your age when diagnosed, cancer stage, type of cancer, and treatment received.
Yes, there are life insurance companies that specialize in underwriting for individuals with cancer.
Not always. Many lower-stage thyroid cancers are insurable as soon as 3 months after treatment.
When cancer comes back, the postponement period is typically 5 years from the completion date of all treatment.
9. Common Mistakes to Avoid
- Applying too soon after completing treatment.
- Not getting underwriting feedback first (Quick Quote) before applying.
- Working with only one company vs. shopping around.
Pro Tip: We utilize a Quick Quote process that enables us to obtain underwriting feedback within days from all competitive companies for thyroid cancer.
Final Thoughts: Next Steps for Thyroid Cancer Survivors
Thyroid cancer doesn’t close the door to life insurance.
- Early-stage cancers qualify for coverage in 3-12 months after treatment.
- Aggressive cancers may face declines, but guaranteed issue policies are available.
- Rates improve as more time passes since completing treatment.
Here’s what to do next:
- Work with a high-risk life insurance broker to shop the best carriers
- Gather your medical history and follow-up results
- Don’t delay — a younger age means lower premiums
- Submit your request to us today.
Ready to compare options? Request your quote today.